
The simplest way to save more is to move money to savings right after you get paid. If I set up an automatic transfer, split my paycheck, or turn on round-ups, I save without having to remember it each time.
Here’s the short version:
- Automatic saving beats manual saving because it removes the choice to spend first.
- Recurring transfers often save more than round-ups alone: $167.84 per month vs. $80.36.
- Direct deposit splits send money to savings before it reaches checking.
- Round-ups are easy to turn on, but they usually grow more slowly.
- A high-yield savings account can pay 4.00% APY or more, while many standard savings accounts average 0.39% APY.
- A simple starting point is $25 per paycheck or even $1 per day.
- I should review my setup every 3 to 6 months and increase the amount when my income goes up.
If I want this to work, I need to do three things: pick one goal, choose one automatic method, and set the timing around payday so I don’t run my checking account too low.
The article below walks through the main options, how to set them up, and how to keep the plan going.
Automate Your Savings (Make it happen without thinking about it)
sbb-itb-0a60575
The Main Ways to Save Money Automatically
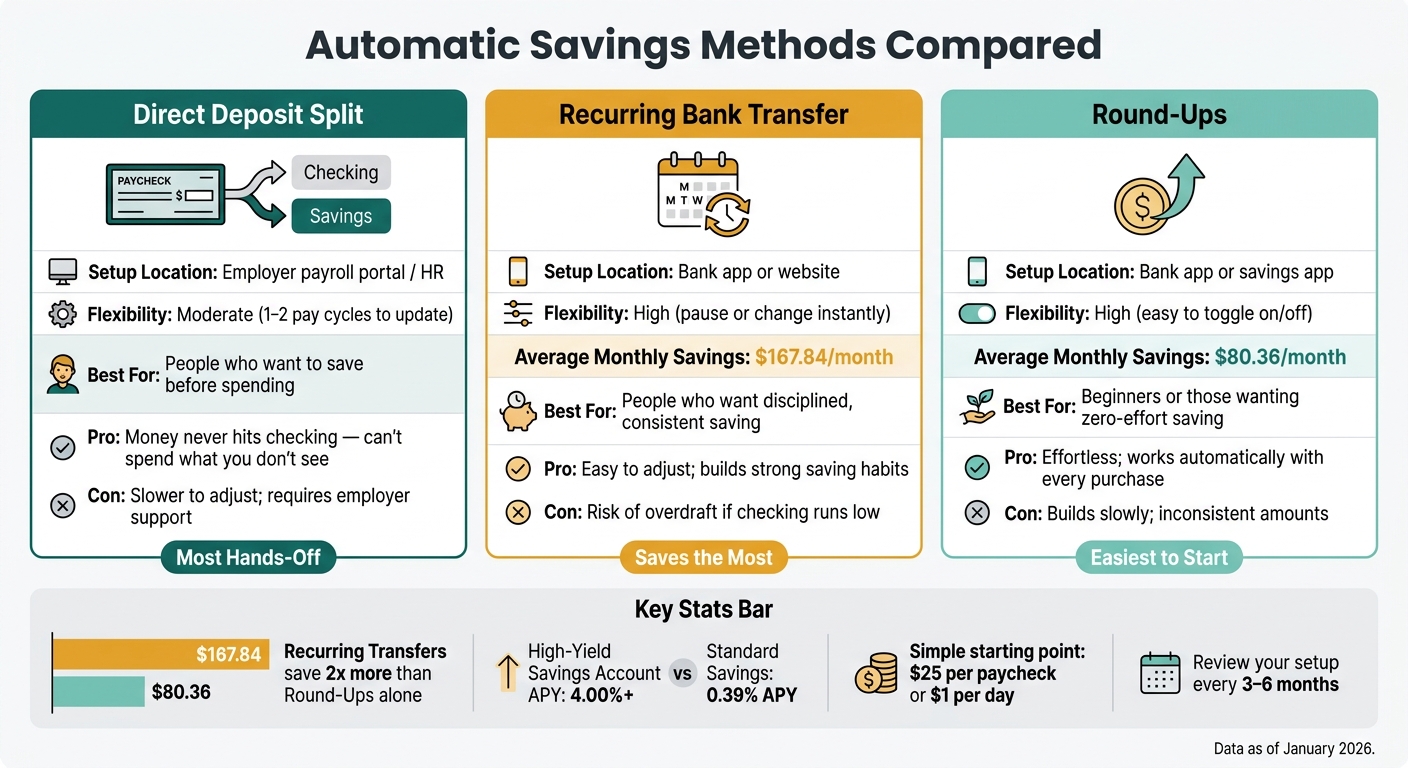
Automatic Savings Methods Compared: Which One Saves You More?
Three common ways to automate saving are direct deposit splits, recurring transfers, and round-ups. The best pick depends on how you get paid and how much control you want over changes.
| Method | Setup Location | Flexibility | Main Pros | Main Cons |
|---|---|---|---|---|
| Direct Deposit Split | Employer payroll portal / HR | Moderate (requires 1–2 pay cycles to update) | Money never hits checking; saves before you can spend it | Harder to adjust quickly; requires employer support |
| Recurring Transfer | Bank app or website | High (can be paused or changed instantly) | Builds disciplined habits; easy to adjust | Risk of overdraft if checking balance runs low |
| Round-Ups | Bank app or savings app | High (easy to toggle on/off) | Zero effort; saves while you spend | Accumulates slowly; inconsistent amounts |
Split Your Direct Deposit Between Accounts
A direct deposit split tells your employer’s payroll system to send part of your paycheck straight to savings before the rest lands in checking. That matters for one simple reason: if the money never shows up in checking, you’re less likely to spend it.
This setup works well for people who want to save first and not think about it again. The tradeoff is speed. If you want to change the amount later, updates usually take one to two pay cycles.
Set Up Recurring Bank Transfers or Round-Ups
A recurring bank transfer moves a set amount from checking to savings on a schedule you choose, such as weekly, biweekly, or monthly. The smart move is to line up the transfer with your payday so the cash is there when the transfer hits and you don’t get stuck with overdraft fees.
This method tends to work better than many people expect. Research found that people using scheduled transfers saved an average of $167.84 per month, compared with $80.36 for people using round-ups by themselves. That’s more than double.
Round-ups are the easy, low-lift option. Your bank rounds each debit card purchase up to the nearest dollar and sends the difference to savings. It’s simple and almost invisible day to day, but the total builds more slowly because the amounts change with your spending.
Choose the Right Account for Your Savings
Where your savings go matters almost as much as the setup itself. As of January 2026, traditional savings accounts averaged just 0.39% APY, while high-yield savings accounts (HYSAs) offered 4% or more.
For short-term goals, a HYSA gives you a better rate while keeping your money easy to access. For long-term goals, it makes more sense to use the account built for that job, like an IRA for retirement or a 529 plan for education.
Once the money has a place to go, the next step is setting the transfer amount and schedule.
How to Set Up Automatic Savings Step by Step
You can set this up in just a few minutes. The key is to choose one auto-saving method and keep it simple.
- Pick one goal and a transfer amount you can stick with
- Set up one transfer method
- Check how it works during the first month
Pick One Goal and a Transfer You Can Keep
Start with one clear goal instead of trying to save for several things at the same time.
After that, look at your monthly income and your must-pay expenses. You want a transfer amount that fits your budget and doesn’t leave your checking account short. If you need a starting point, $25 per paycheck is a good place to begin. Another trick that helps: think of the amount in smaller terms. $1 a day can feel easier to handle than $30 a month.
Once you’ve picked the amount, choose the transfer date.
Set Up the Transfer in Your Bank or Payroll Portal
Use your bank if you want recurring transfers. Use payroll if you want to split your direct deposit.
In your bank’s app or website, go to "Transfers" or "Scheduled Transfers." Pick the account the money will come from, the account it will go to, and the start date. If you’re sending money to a savings account at another bank, you’ll need that bank’s routing number and your account number. Set the transfer for payday or the day after. That timing can help cut down on overdraft risk.
If you’re using direct deposit, go through your employer’s payroll portal or HR team. You’ll need your savings account number and your bank’s routing number. In some cases, you may also need a voided check. This update usually takes one to two pay cycles to show up.
Check, Monitor, and Adjust During the First Month
For the first month, keep an eye on your checking balance. Make sure the transfer date doesn’t bump into automatic bill payments. It’s also smart to turn on a low-balance alert. That way, you can lower the transfer amount or shift the date before an overdraft happens.
How to Keep Your Automatic Savings Plan Going
Once your transfer is set up, the next step is simple: make sure it keeps working in real life.
The best automatic savings plan isn’t the biggest one. It’s the one you can stick with. If the transfer amount is too high, you might end up pulling money back out of savings just to cover bills. That cancels out the whole point. A plan that fits your day-to-day spending is much easier to keep in place over time.
Start Small and Increase Your Savings Over Time
What matters most is consistency, not a big starting number.
A smart way to build your savings over time is to bump up your automated transfer by 1% to 2% whenever you get a pay raise. If your income shifts or you finish paying off a debt, take another look and see whether your checking account can still handle a larger transfer after bills are paid.
Even small increases can add up when you leave them in place.
Once the transfer feels steady, give each dollar a clear job by splitting your savings by goal.
Use Separate Savings Buckets for Each Goal
When all your savings sits in one account, it’s harder to tell what money is for emergencies and what money is meant for something else. That’s where labeled savings buckets help. They make each transfer more concrete, and they make progress easier to see.
You can set up separate sub-accounts or labeled buckets for goals like Emergency Fund, Travel, Annual Insurance, or Tax Reserve. Some banks let you do this inside one high-yield savings account, which means you can stay organized without dealing with a bunch of different logins.
| Approach | Pros | Cons |
|---|---|---|
| One general savings account | Simple to manage; easy to track total balance | Harder to monitor goal progress; easier to overspend earmarked funds |
| Multiple goal-based buckets | Clear visibility per goal; reduces accidental spending | More complex to set up; may require monitoring multiple sub-accounts |
Review Your Setup Every Few Months
You don’t need to check your system every week. After the first month, a lighter review schedule usually works better.
A quick check-in every three to six months can help keep your setup lined up with your budget and savings goals. Look at whether the transfer amount still feels doable, whether your goals have changed, and whether you’ve had any overdrafts or surprise withdrawals from savings.
It also helps to leave a cash cushion in your checking account. That gives you some breathing room, so small changes stay small instead of turning into repeated overdraft problems. And if you finish one goal, move that transfer straight to the next one.
Conclusion: Make Saving Automatic and Let It Work for You
Automatic saving works for a simple reason: it takes the choice off the table. Your money moves before you have a shot at spending it. Once that transfer is set up, saving starts to happen in the background.
From there, the job is pretty simple. Stick with it, and make small changes when your income or bills shift. That steady habit is what keeps the system going.
Research shows that people using fixed, recurring transfers saved an average of $167.84 per month – more than double the $80.36 saved by those relying on round-up methods alone. That gap comes down to consistency, not how big the transfer is.
Even $1 a day turns into $365 a year, and a high-yield savings account can help that money grow more over time. Start small, make it automatic, and let time do the heavy lifting.
FAQs
Which automatic savings method should I start with?
Start by setting up recurring transfers from your checking account to your savings account. Most banks let you do this in just a few minutes through their website or app.
Keep the amount small at first, like $5 or $10. That makes the habit easier to keep. When it starts to feel normal, you can slowly increase the amount over time.
How much should I automate from each paycheck?
Start small, especially if money is tight. A lot of people begin with about 5% of their take-home pay, or even just $5 or $10 from each paycheck.
What matters most is sticking with it. Once saving starts to feel easier, bump the amount up little by little and aim for a long-term savings rate of 15%–20%, including retirement contributions.
How can I avoid overdraft fees with automatic transfers?
Schedule transfers 1–2 days after payday, not on the same day. That small gap gives your paycheck time to clear and can help you avoid annoying timing issues.
It also helps to keep a $100–$200 buffer in your checking account for surprise charges or bank processing delays.
If you do overdraft, don’t cancel the transfer right away. Lower the amount for a bit and get it back on track when your balance settles.
Check your balance often in your bank’s app or on its website so you can spot problems early.
Related Blog Posts
- Why Budgets Fail: Common Mistakes Explained
- 10 SMART Financial Goal Examples
- How to Rebuild an Empty Emergency Fund
- How to Budget for Big-Ticket Items
Karla Moss is a CPA and former startup Controller who spent 15 years managing finance at the executive level — including inside a company that grew to unicorn status. She founded Karla & Co. to bring real-world financial clarity to everyday money decisions. She’s based in Phoenix, AZ and writes from personal experience as much as professional expertise.