
Canceling paid credit monitoring services can save you money and simplify your finances, especially if you’re no longer using the service. Here’s how to do it:
- Identify the Billing Source: Check if charges come from third-party platforms (e.g., Apple, PayPal) or directly from the service provider.
- Gather Account Details: Collect your account number, email, and plan name. Review recent statements to confirm charges.
- Find Your Billing Date: Log in to your account or check statements to know when the subscription renews.
- Cancel Online or by Phone: Most services allow cancellation via your account dashboard or customer service. Always request a confirmation number.
- Monitor for Charges: Check your bank or credit card statements to ensure no further billing occurs.
To avoid future charges, cancel at least a day before the renewal date or free trial ends. If issues arise, dispute charges through your card issuer or file a complaint with the CFPB.
Switch to free tools like AnnualCreditReport.com, Credit Karma, or Experian’s free plan to monitor your credit without paying. For added security, consider freezing your credit with all three major bureaus.
How To Cancel Credit Monitoring On TransUnion (How Do I Cancel TransUnion Credit Monitoring?)
sbb-itb-0a60575
Before You Cancel: What to Do First
Taking the time to prepare before canceling a service can save you from unexpected charges and provide a clear record if issues arise. Devote 15–20 minutes to gather the necessary details for a smooth cancellation process.
Gather Your Account Information
Start by identifying the service and where the billing originates. This isn’t always straightforward – many people realize their credit monitoring charges aren’t billed directly by a credit bureau like Equifax, Experian, or TransUnion. Instead, they may come through third-party platforms such as the Apple App Store, Google Play, PayPal, or even Amazon. Since cancellations must be handled through the billing platform, figuring this out first can save you a lot of time and frustration.
Once you’ve pinpointed the billing source, collect the essentials: the email associated with the account, your membership or account number, and the exact name of your plan (e.g., "IdentityForce UltraSecure" instead of just "standard plan"). Next, check your bank or credit card statements from the last two to three months to locate the recurring charge. Don’t forget to review PayPal’s Automatic Payments and subscriptions tied to mobile app stores. As noted by The Penny Hoarder:
"You cannot cancel what you cannot see. Most people underestimate their subscription total because the charges are spread across multiple platforms." – The Penny Hoarder Staff
Find Your Next Billing Date
Knowing your renewal date is crucial. Log in to your account and navigate to sections like "Settings", "Billing", or "Subscription" to find this information. If it’s not listed, review your bank statements to identify when the charge typically appears – whether it’s monthly, quarterly, or annually.
Set a calendar reminder for two days before the renewal date to avoid unwanted charges. This is especially important for free trials, as some convert to paid subscriptions immediately at the end of the trial period, sometimes even before the day officially ends.
Save Your Account Details
Before canceling, save all relevant account details. Take screenshots of your account dashboard, plan information, recent credit alerts, and any terms showing your renewal date. If your plan includes identity theft insurance, download or save the policy summary, as you may need it to report any issues within 90 days.
These records can also protect you if charges continue after cancellation. A screenshot of your plan details and a cancellation confirmation number can serve as strong evidence in a billing dispute. When canceling in writing, use clear language such as: "I am revoking any authorization for future recurring charges to my payment method". This phrasing aligns with dispute codes used by Visa and Mastercard, which can be helpful if you need to escalate the issue.
With everything in place, you’ll be ready to move forward with canceling your service.
How to Cancel a Paid Credit Monitoring Service
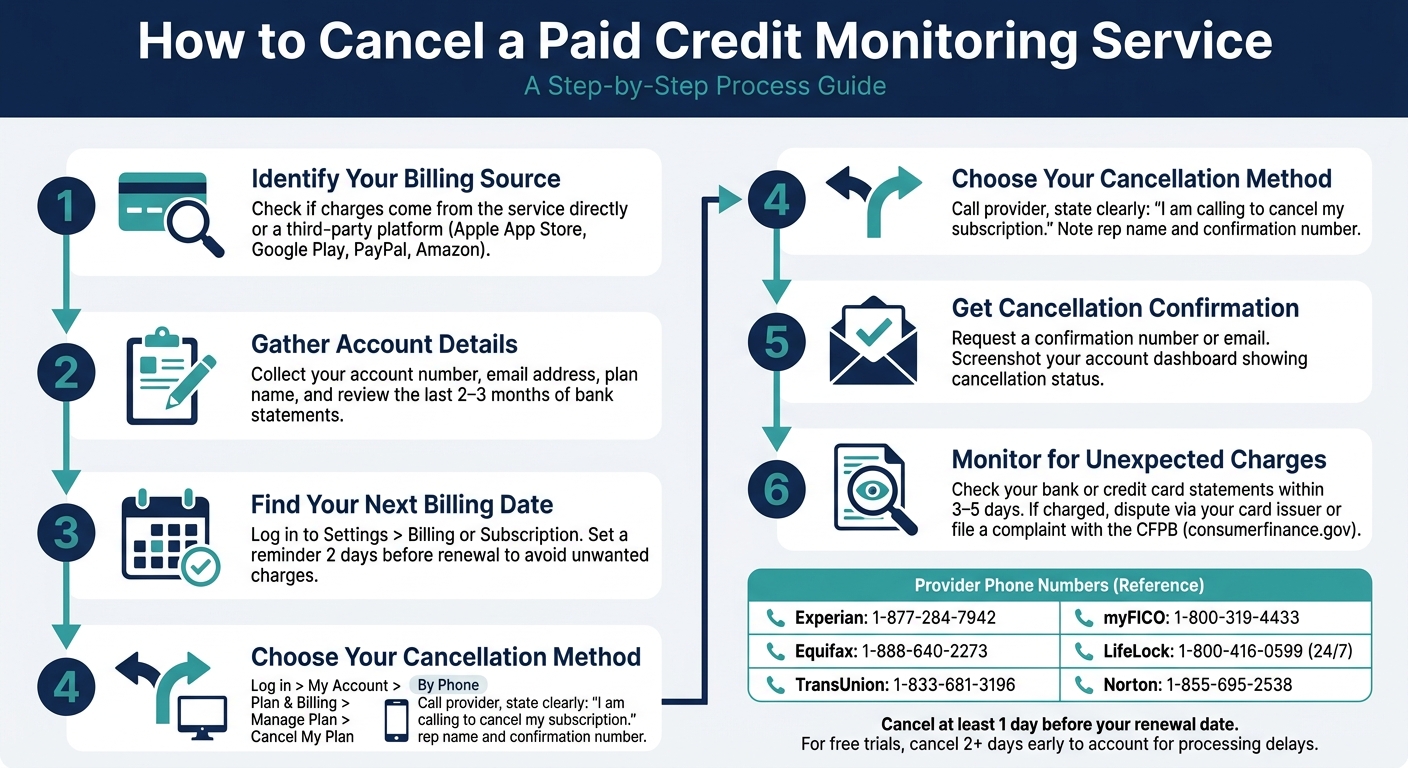
How to Cancel a Paid Credit Monitoring Service: Step-by-Step Guide
Canceling a credit monitoring service can be straightforward if you know where to start. Most services offer three main ways to cancel: online through your account dashboard, by phone, or by canceling a free trial before charges begin. The method you choose will depend on how your service is billed.
Canceling Online Through Your Account
Many credit monitoring services let you cancel directly from your online account. Look for sections like "My Account", "Plan & Billing", or "Subscription" in your account settings. Here’s the typical process:
- Log into your account.
- Navigate to "My Account" or "Plan & Billing."
- Click on "Manage Plan."
- Select a reason for canceling from the dropdown menu (if required).
- Confirm your cancellation by clicking "Cancel My Plan."
After completing these steps, you should receive a confirmation email. Before finalizing the cancellation, download any important documents, such as credit reports, monitoring alerts, or identity theft restoration files. Keep in mind that once your subscription ends, access to these materials is usually revoked. If you’re on a family plan, be aware that canceling will also remove coverage for all linked members.
Canceling by Phone
Some services require you to cancel by phone, or you might prefer speaking with a representative. Before calling, gather your account number, the email tied to your account, and your reason for canceling. During the call, note the representative’s name and your cancellation confirmation number for your records.
When you speak to the representative, state your request clearly: "I am calling to cancel my LifeLock subscription." Avoid hesitant language to minimize retention efforts. If they offer discounts and you’re not interested, respond politely but firmly: "I understand, but I would like to cancel my account today."
Before ending the call, confirm with the representative: "Can I have my cancellation confirmation number and your name, please?" Afterward, monitor your bank or credit card statement within 3–5 days to ensure no additional charges have been applied.
Here are the contact details for some common providers:
| Service Provider | Phone Number | Operating Hours (ET) |
|---|---|---|
| Experian | 1-877-284-7942 | Not specified |
| Equifax | 1-888-640-2273 | Mon–Sun: 8 a.m. – 3 p.m. |
| TransUnion | 1-833-681-3196 | Mon–Fri: 8 a.m. – 9 p.m.; Sat–Sun: 8 a.m. – 5 p.m. |
| myFICO | 1-800-319-4433 | Mon–Fri: 9 a.m. – 9 p.m.; Sat: 10 a.m. – 7 p.m. |
| LifeLock | 1-800-416-0599 | 24/7 |
| Norton | 1-855-695-2538 | Business hours |
If your credit monitoring service is bundled with another product, like Norton 360 with LifeLock, remember that canceling one service doesn’t automatically cancel the other. You may need to contact separate departments to ensure all charges are stopped.
Canceling a Free Trial Before It Converts
Free trials often work as “negative options,” meaning you’ll be charged automatically if you don’t cancel before the trial ends. The Federal Trade Commission advises:
"If you sign up [for a free trial], make a note on your calendar to remind you to cancel before the trial ends."
Set a reminder at least two days before the trial expires to account for time zone differences or processing delays. Check the terms and conditions carefully to confirm the trial length and the required cancellation method. Some services may only allow cancellations by phone, even during a trial period.
When signing up, uncheck any pre-selected options that could result in extra charges. If you notice a charge after the trial ends, contact your credit card issuer to dispute it as an unauthorized transaction.
Avoiding Extra Charges and Getting Refunds
How Billing and Refund Policies Typically Work
Most services charge the full monthly fee upfront, with no refunds for unused days if you cancel mid-cycle. For example, Equifax’s Terms of Use explicitly state:
"Cancel your monthly subscription and receive no refund; service continues for the remainder of the billing month."
Annual plans, however, often operate differently. With Equifax, for instance, you may receive a pro-rated refund based on the number of unused months remaining. Let’s say you purchase an annual plan on January 1 and cancel on February 1. In this case, you’d retain access until March 1 but receive a refund for the ten unused months from March through December. On the other hand, one-time credit report purchases are typically non-refundable once delivered.
How to Avoid Being Charged After Canceling
To steer clear of extra charges, make sure to cancel your subscription at least one day before your next billing date. Your billing date is usually tied to the day you signed up. For example, if you signed up on the 15th, aim to cancel by the 14th.
If you’re on a free trial, cancel at least a day before the trial ends to avoid being charged automatically. For instance, Experian charges $24.99 monthly if you don’t cancel within their 7-day trial period.
After canceling, keep an eye on your statements during the next billing cycle to ensure no unexpected charges appear.
How to Dispute a Charge or File a Complaint
If you notice an unauthorized charge, start by contacting the service provider. Keep thorough records of your interactions, including dates and the names of representatives you speak with. If the issue isn’t resolved, escalate the matter by reaching out to your bank or credit card issuer to dispute the charge. Under the Fair Credit Billing Act (FCBA), you have 60 days from the charge date to file a dispute. Your card issuer must acknowledge your claim within 30 days and resolve it within 90 days.
For unresolved issues, consider filing a complaint with the Consumer Financial Protection Bureau (CFPB) at consumerfinance.gov. As consumer debt expert Steve Rhode explains:
"A CFPB complaint often prompts the company to respond or refund just to close the complaint."
You can also report the problem to the Federal Trade Commission (FTC) at ReportFraud.ftc.gov or contact your state’s Attorney General. If the disputed amount is substantial, small claims court might be an option. In most states, you can file claims ranging from $5,000 to $10,000 without needing an attorney.
Once your billing issues are sorted out, you can explore safer ways to monitor your credit.
How to Monitor Your Credit After Canceling
After canceling a paid credit monitoring service, it’s crucial to keep an eye on your credit to ensure financial security. Setting up reliable monitoring tools and routines can help you stay informed and prevent future issues.
Use Free Credit Reports
Start by using AnnualCreditReport.com, the official site where you can access your full credit reports for free from Equifax, Experian, and TransUnion. For regular updates between these comprehensive checks, pair Credit Karma (which monitors Equifax and TransUnion weekly) with a free Experian account to cover all three bureaus.
Keep in mind that Credit Karma and Chase Credit Journey provide a VantageScore 3.0, while many lenders rely on FICO scores. If you need to see a FICO score, Experian’s free plan and Discover’s Credit Scorecard both include one.
| Service | Bureaus Covered | Score Type | Frequency |
|---|---|---|---|
| Credit Karma | Equifax, TransUnion | VantageScore 3.0 | Weekly |
| Experian Free | Experian | FICO Score | Monthly |
| Chase Credit Journey | TransUnion | VantageScore | Weekly/Monthly |
| Discover Scorecard | Experian | FICO Score | Monthly |
For added security, consider taking steps beyond just checking your credit reports.
Use Credit Freezes and Fraud Alerts
If you don’t plan to apply for new credit soon, a credit freeze is a strong protective measure. It prevents creditors from accessing your credit file, effectively stopping anyone from opening new accounts in your name – even if they have your personal details.
"A credit freeze is free, permanent, and more effective than monitoring at preventing new account fraud." – Crowned Credit Blog
Freezing your credit is free and can be done through all three major bureaus. It remains in place until you decide to lift it. Here’s where to freeze your credit:
- Equifax: https://www.equifax.com/personal/credit-report-services/credit-freeze
- Experian: https://www.experian.com/freeze/center.html
- TransUnion: https://www.transunion.com/credit-freeze
If you need a less restrictive option, consider a fraud alert. This prompts creditors to verify your identity before issuing credit. Fraud alerts are free, last for one year, and require contacting only one bureau, which will notify the others.
Both credit freezes and fraud alerts are excellent tools to reinforce your financial defenses.
Set Up Your Own Credit Monitoring Routine
To stay proactive, create a personalized routine:
- Use Credit Karma for weekly updates from Equifax and TransUnion.
- Check your free Experian account monthly for updates.
- Pull full reports from AnnualCreditReport.com every few months for a comprehensive review.
Enable real-time alerts for new inquiries and account openings to catch potential issues early. Many credit card issuers also offer score tracking through their apps, which can be a convenient addition to your routine.
With 2.8 million identity theft reports filed last year and fraud losses totaling over $5.8 billion, as reported by the FTC, keeping tabs on your credit isn’t just a precaution – it’s a necessity.
Key Takeaways
Canceling a paid credit monitoring service is simple, but there are a few steps to keep in mind. First, double-check your billing date and make sure to get a cancellation confirmation to avoid any unexpected charges. Keep in mind that some services, like Equifax, clearly state they do not offer refunds for partial months.
Once you cancel, it’s important to take immediate steps to protect your credit. Switching to free options can help you stay secure without the added cost. Start with a credit freeze at all three major credit bureaus – it’s free and one of the best ways to prevent new account fraud. Combine this with free credit reports available at AnnualCreditReport.com and free monitoring tools like Capital One’s CreditWise or Chase Credit Journey.
Don’t forget to review your bank statements after cancellation. If you notice an unexpected charge, contact the service directly. If they don’t resolve it, you can escalate the issue to your card issuer or the CFPB.
For more tips on managing your credit, visit Karla & Co.. Their resources cover credit management, debt strategies, and budgeting, all explained in clear, easy-to-understand language by a CPA with real-world financial experience.
FAQs
How do I find out who is actually billing me for the service?
To spot recurring charges or unfamiliar merchant names, start by reviewing your recent credit card or bank statements. For PayPal users, head to Settings > Payments > Manage Automatic Payments to see a list of authorized services. If you rely on Apple or Google, check subscription details in your device or app store settings. These steps can help you trace the billing source, particularly for subscriptions or direct debits.
What should I do if I’m still charged after I cancel?
If you’re billed after canceling a paid credit monitoring service, take action to get your money back. Start by requesting a refund – provide your cancellation date and confirm you haven’t used the service since canceling. If the company denies your request, you can dispute the charge with your credit card issuer. Be sure to do this within 60 days of the charge appearing on your statement.
Keep detailed records of all communications, including dates and what was discussed. If needed, send a written notice to the company to back up your claim and strengthen your case. This extra step can be helpful if the issue escalates.
Will canceling remove my credit freeze or fraud alert?
Canceling a paid credit monitoring service won’t automatically lift a credit freeze or remove a fraud alert. These are independent security measures that you’ll need to manage directly with the credit bureaus. To make changes, you’ll have to reach out to Equifax, Experian, or TransUnion. While canceling the monitoring service will stop alerts, it won’t impact any existing freezes or fraud alerts unless you take deliberate steps to modify or remove them.
Related Blog Posts
- How Overdraft Fees Work And How To Avoid Them
- Paying Collections: Does It Improve Credit Scores?
- 5 Steps to Switch Banks Easily
- Why Shopping Insurance Rates Saves Money
Karla Moss is a CPA and former startup Controller who spent 15 years managing finance at the executive level — including inside a company that grew to unicorn status. She founded Karla & Co. to bring real-world financial clarity to everyday money decisions. She’s based in Phoenix, AZ and writes from personal experience as much as professional expertise.